
The global sunflower oil market is expected to face a decline in export supplies toward the end of 2026, despite a large sunflower seed harvest in major producing countries. According to Germany-based analysts Oil World, global sunflower oil exports are forecast at around 3.96 mln tons in September–December, compared with 4.46 mln tons during the same period last year. Given the abundant sunflower seed crop, potential export volumes could have reached 5.1 mln tons.
Logistical disruptions in the Black Sea region remain the main factor limiting global trade, with shipment difficulties expected to persist at least until December. According to analysts, Ukraine is projected to export only 950 thsd tons of sunflower oil in September–December, down from 1.37 mln tons a year earlier. Meanwhile, Russian exports are forecast at 1.05 mln tons, compared with 1.48 mln tons during the corresponding period last year.
As a result, combined sunflower oil exports from Ukraine and Russia during the first four months of the MY 2026/27 could decline to approximately 2 mln tons. This would be around 800 thsd tons below last year’s level and the lowest volume in 11 years. The reduction in supplies from two major exporters is creating new opportunities for alternative suppliers and reshaping international vegetable oil trade flows.
Argentina could become one of the main beneficiaries of this shift as the country continues to expand sunflower seed crushing. Oil World forecasts that Argentine sunflower oil exports will reach a record 600–620 thsd tons in September–December. Sunflower seed processing is also expected to increase in Bulgaria, Romania and Turkey. Bulgaria is already expanding its sunflower oil exports, while higher domestic crushing volumes in Turkey are expected to reduce the country’s dependence on imported sunflower oil.
However, additional supplies from alternative origins are unlikely to fully offset the decline in Black Sea exports. Reduced sunflower oil availability could encourage major importers, particularly India and China, to increase purchases of other vegetable oils. Palm oil is expected to benefit the most from this shift, with demand potentially strengthening in the final months of 2026 as global vegetable oil trade patterns continue to change.

SOFIA/BRUSSELS. Logistical challenges are driving up prices. Turkey is increasing imports from the EU. Kazakh sunflower seeds are under pressure from a record crop in Russia.
Stable prices at origin
As of 19 October 2026, Ukrainian farmers had harvested 79% of the sunflower seed crop. A production total of 9.077 million mt has been achieved so far across an area of 4.123 million hectares, resulting in an average yield of 2.2 mt/ha (+18.9% compared with last year). At this time last year, harvest progress was only 3 percentage points ahead; a total of 7.838 million mt of sunflower seeds had been produced across 4.24 million hectares, meaning the average yield was significantly lower at 1.85 mt/ha.
Prices for Bulgarian bakery kerne...
Ukraine is prioritising vegetable oil exports in logistics. Learn how this supports crushing margins, shifts demand from grain to oilseeds and affects sunflower prices.
Ukraine’s new priority regime for vegetable oil logistics is a structural bullish factor for sunflower seeds and kernels, as domestic crushing gains protection in a constrained export environment, while grains face growing competition for rail and port capacity.
The decision to fast-track sunflower and other vegetable oils through rail, ports, border crossings and the Sulina Canal shifts scarce logistics capacity towards higher-value oil exports during wartime. This should help keep Ukrainian sunflower crushers running, stabilise demand for seeds and other oilseeds, and partially decouple the sunflower complex from the downside pressures hitting grain exports. Near-term, the policy reinforces sunflower’s value chain economics (around six times higher export revenue per tonne than wheat or maize), but also raises the risk of tighter grain logistics and potentially more volatile Black Sea price spreads.
Spot indications in Europe and the Black Sea remain relatively stable to slightly firmer along the sunflower value chain.
- Sunflower seeds, black, 98% purity, origin MD, FCA Rheinfelden Herten, DE are quoted at 0.45 EUR/kg (previously 0.44 EUR/kg).
- Sunflower seeds, striped, 98% purity, origin BG, FOB Sofia stand at 0.75 EUR/kg (0.74 EUR/kg previously), while black seeds FCA Sofia are steady at 0.44 EUR/kg.
- Crude sunflower oil from UA, CPT Odesa, is last indicated at 1.032 EUR/kg (16 October 2026), slightly below earlier mid-October values, suggesting crushers’ margins remain sensitive to oil price fluctuations.
- Bakery-grade hulled kernels show a mixed picture: UA FCA Dnipro at 0.90 EUR/kg (unchanged), BG FCA Berlin at 1.08 EUR/kg (up from 0.92 EUR/kg), and MD FCA Rheinfelden Herten at 0.93 EUR/kg (stable).
Ukraine’s government has introduced a temporary mechanism giving priority to vegetable oil exports, including sunflower oil, across key logistics channels. Oil shipments now receive...

Kazakhstan's State Inspection Committee in the Agro-Industrial Complex of the Ministry of Agriculture has sent an official request to Russia's Federal Service for Veterinary and Phytosanitary Supervision asking it to temporarily suspend the issuance of certificates for imported sunflower seeds from October 23, 2026.
The Kazakh side has expressed concern over quarantine and phytosanitary safety following an increase in cases of quarantine pests being detected in oilseed shipments from Russia. According to the committee, 23 cases of sunflower phomopsis (Diaporthe helianthi) were recorded in 2025 and the elapsed period of 2026.
Russia accounts for the bulk of sunflower seed imports and is the key supplier of the product to the Kazakh market.
To prevent the introduction and spread of quarantine pests, Rosselkhoznadzor has been asked to temporarily suspend the issuance of phytosanitary certificates for seed and food-grade sunflower seeds shipped from Russia to Kazakhstan from October 23, 2026.
The committee said the measure was preventive in nature and aimed solely at ensuring quarantine and phytosanitary safety and protecting the country's agricultural production. The committee and its regional inspectorates are currently conducting an additional analysis of the phytosanitary situation.
According to APK-Inform, citing official statistics, Kazakhstan imported around 137 thousand tons of sunflower seeds in total in the 2025/26 MY.
Russia was traditionally the main supplier, accounting for 122 thousand tons. Imports from Russia declined slightly from the previous season, when they totaled 129 thousand tons.
Ukrainian agricultural producers have already completed the harvest of three crops: 25.5 million tonnes of wheat, 6 million tonnes of barley and 4 million tonnes of rapeseed have been harvested.
This was reported by Taras Vysotskyi, Minister of Agrarian Policy and Food of Ukraine, during his weekly briefing with journalists.
According to him, the harvesting of sunflower, soybeans and corn is currently ongoing. In particular, sunflower has been harvested from 80% of the area, soybeans from more than 85%, and corn from 20% of the area.
«The sunflower and soybean harvest will be effectively completed by the end of October. The corn harvest, naturally, will continue in November and December. The forecast figures for these crops are as follows: soybean production is expected to reach up to 4 million tonnes, while sunflower production is expected at 12 million tonnes. Given that 4 million tonnes of rapeseed have been harvested, we can speak of 20 million tonnes of oilseeds,» Taras Vysotskyi noted.
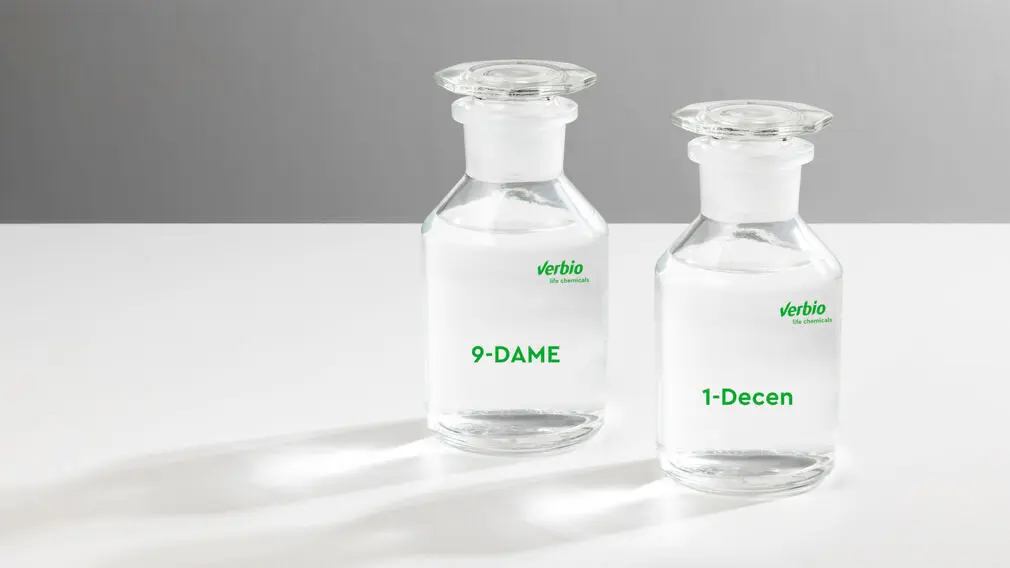
Leading German biodiesel producer Verbio has moved into the renewables sector after opening a large-scale plant for rapeseed-based chemicals at its Bitterfeld site in Germany.
Once fully operational, the new €100M (US$112M) plant would be capable of producing up to 60,000 tonnes/year of bio-based chemicals for use as an alternative to fossil-based raw materials in lubricants, detergents and cleaning products, as well as plastics, the company said on 6 October.
In addition to being used in biodiesel production, rapeseed methyl ester produced at the site would be used as a raw material in the production of higher-value chemicals.
Following commissioning, market ramp-up would begin in stages with 1-decene and 9-DAME as the first products, the company said.
“With this new production plant, we are supplementing our biorefinery with a further stage in the value chain,” said Verbio CEO Claus Sauter.
“By processing European rapeseed oil, we are strengthening regional agriculture and reducing our reliance on global supply chains that are prone to disruption.”
The process at the plant relies on ethenolysis, a form of olefin metathesis, with catalysts from Verbio’s Hungarian subsidiary XiMo converting carbon compounds in rapeseed methyl ester into new molecules.
Verbio said the investment came against a backdrop of challenges in the European chemical industry, including increased international competition, high production costs and the need to shift to a new raw materials base.
Headquartered in Zörbig, Germany, with an administrative office in Leipzig, the company operates production sites in Europe, North America and Asia.
According to its website, Verbio has an installed production capacity of 710,000 tonnes/year of biodiesel, 800,000 tonnes/year of bioethanol and 1,980 GWh/year of biomethane.
Global soybean and sunflower oil markets remain influenced by growing supplies and expectations of stronger import demand. December soybean oil futures on the Chicago Board of Trade (CBOT) declined by 1.9% over the past week to $1,470/t. Prices have fallen by 3.2% over the month, although they remain 30.8% higher year-on-year. The main factors weighing on the market were an upward revision to the US soybean production forecast and a 2.8% weekly decline in soybean prices.
Additional pressure came from a 4.5% decline in US soybean crushing in September to 5.34 mln tons, which was significantly below analysts’ expectations. Meanwhile, the market showed little reaction to a 12.4% reduction in US soybean oil stocks from the end of August to 478 thsd tons, the lowest level since November 2014. In Brazil, spot soybean oil prices remained at $1,220–1,240/t FOB during the week, while Argentine soybean oil was offered at $1,200–1,220/t FOB. On China’s Dalian Commodity Exchange, futures declined by $15–20/t to $1,315–1,320/t.
The sunflower oil market is showing somewhat different dynamics, supported by demand from India. Over the past week, Indian bid prices for sunflower oil increased by $10–20/t to $1,400–1,420/t CIF Mumbai, while offers from the Black Sea region stood at $1,435–1,460/t CIF Mumbai. Prices are being supported by a 36% decline in India’s sunflower oil imports in September to 103 thsd tons, the lowest level since April 2022. The reduction in shipments was linked to disruptions at Black Sea ports in Ukraine and Russia, limiting product availability for Indian buyers.
In Ukraine, sunflower oil prices declined over the week to $1,000–1,100/t FCA plant due to further increases in road and rail transportation costs to ports and EU buyers. Meanwhile, bid prices for Ukrainian sunflower oil delivered to the European Union remain at $1,340–1,360/t. Increasing domestic supplies are limiting the potential for further price growth. At the same time, competition from Argentina is intensifying, with Argentine sunflower oil offered at $1,300–1,330/t FOB for November–December delivery and $1,250–1,290/t FOB for February–April delivery.
Meanwhile, the outlook for the global sunflower oil market is supported by expectations of stronger demand from India. According to the Indian sunflower oil producers’ association, the country’s sunflower oil imports are forecast to increase by 30% to 3.5 mln tons in the MY 2026/27, while soybean oil imports could decline by 10.7% to 5 mln tons. Argentina is also strengthening its position in the Indian market, with its share of sunflower oil supplies rising from 8% to 12% in 2026. For Ukrainian exporters, further growth in Indian demand creates additional sales opportunities, although realizing this potential will depend on the availability of maritime logistics and competitive export prices.
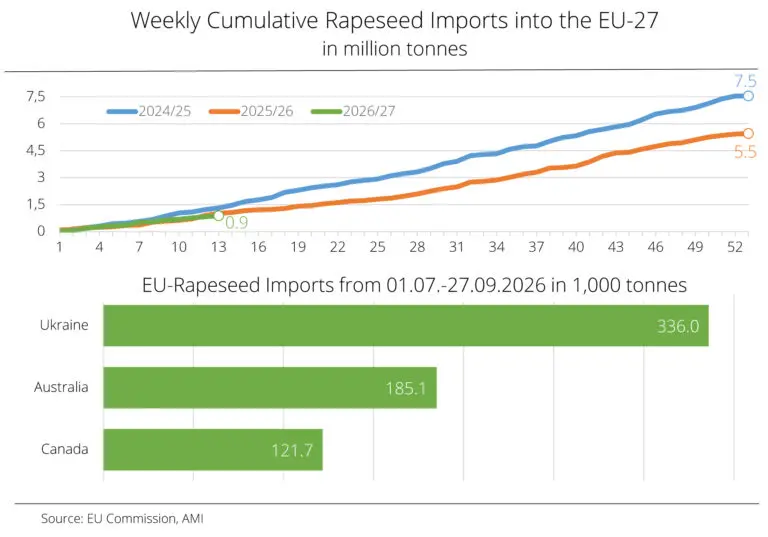
EU rapeseed imports fell sharply at the start of the 2026/27 season, signalling tightening feedstock availability for Europe’s biodiesel and HVO producers despite a smaller domestic harvest.
New figures show that rapeseed arrivals from July to September totalled around 871,500 tonnes, a 14% decline year‑on‑year, with logistical constraints in Ukraine continuing to reshape trade flows.
Ukraine remained the EU’s largest supplier, but volumes dropped significantly. As noted in the source document, “imports remained below the 599,900 tonnes recorded from July through September 2025”, despite a larger Ukrainian harvest.
Ongoing bottlenecks — particularly in seaborne logistics — have forced exporters to rely more heavily on rail, limiting throughput and reducing availability for EU crushers and biofuel producers.
Australia strengthened its position as the EU’s second‑largest supplier, shipping 185,100 tonnes, up 35% on the year.
Canada followed with 121,700 tonnes, a sharp increase from near‑zero levels in 2025. According to UFOP, this shift reflects Ukraine’s constrained export capacity, China’s trade dispute with Canada, and rising freight rates from Australia.
Crucially for the biofuels sector, Canadian rapeseed is largely channelled into renewable fuel production due to restrictions on genetically modified varieties in EU food markets. As the document states, “the biofuels market [is] by far the most important trade channel for Canadian rapeseed oil.”
Canada’s early recognition under the EU’s updated NUTS 2 GHG values further strengthens its role as a compliant supplier for RED III‑aligned biofuel pathways.
With RED III mandating higher renewable fuel quotas through 2026–27, the decline in early‑season rapeseed imports underscores the importance of diversified supply chains and certified feedstock sources.
Market participants will be watching closely to see whether logistical improvements in Ukraine or expanded flows from Australia and Canada can stabilise availability in the months ahead.